BCS launches a dedicated power infrastructure division as European site selection shifts away from FLAP-D hubs
BCS Consultancy has launched a Power Infrastructure division and its senior consultant Nick Marlow spoke at DCD Studio on 12 October 2026 about the practical realities of European data center development.
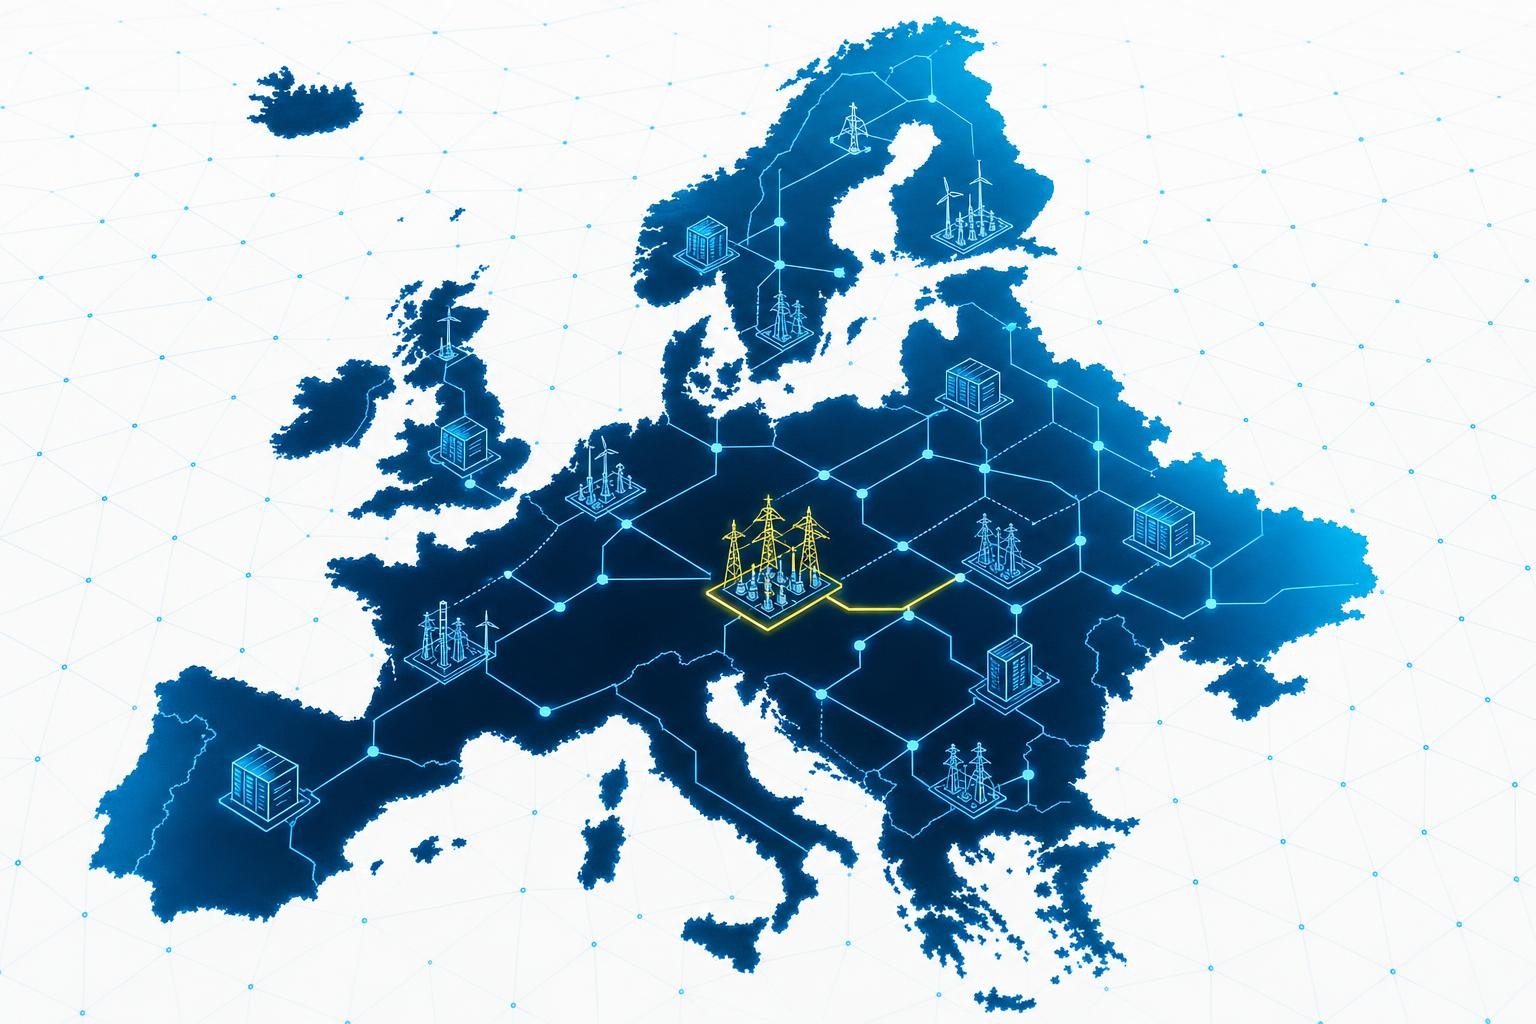
BCS Consultancy launched a dedicated Power Infrastructure division on 11 October 2026, one day before senior consultant Nick Marlow appeared on the Data Center Dynamics DCD Studio programme to discuss practical strategies for European data center development[1]. The timing underlines how central the power question has become: BCS's own Data Centre Truths 2026 survey, drawn from more than 3,000 respondents across 41 countries, found that 93% of industry respondents expect demand to continue rising even as supply becomes harder to secure.
Power access has moved upstream in the development process
The new division, led by Cameron Thompson - previously Head of Utilities - marks a deliberate repositioning. BCS says its power work was previously weighted toward delivering substations for projects that already had grid connections. Client demand has since shifted toward power strategy and identifying routes to unlock developments at an earlier stage. The division now works with investors, landowners, developers, and operators from initial power strategy and grid connection through to substations, cable routes, and microgrids.
The company is explicit about why: grid access alone is no longer sufficient, and developers need confidence that power can be delivered to a site within a commercially viable timeframe. BCS says delays increasingly arise not from a single technical issue but from interfaces between grid connection and delivery - design approvals, cable routes, land rights, long-lead equipment, civils readiness, commissioning, and network witnessing.
FLAP-D saturation is forcing a geographic rethink
The backdrop to Marlow's DCD Studio conversation is a European market under structural pressure[1]. Approximately 62% of Europe's data center capacity is currently located in the FLAP-D markets (Frankfurt, London, Amsterdam, Paris, and Dublin), but that share is expected to fall to 55% by 2030 and 51% by 2035. Grid connection wait times in those hubs now average seven to ten years in the most constrained locations, according to the IEA.
Europe's data center power demand stood at 24.8 GW at the end of 2024 and is projected to reach 45.6 GW by 2030, a compound annual growth rate of more than 10%. That volume of new load cannot be absorbed by the existing FLAP-D footprint. BCS's Data Centre Truths 2026 report identifies the following as the converging constraints now hitting individual projects simultaneously:
- Power availability and grid queue position
- Shortages of skilled construction and commissioning professionals (95% of respondents expect skilled professional availability to decline further)
- Planning complexity and regulatory friction
- Supply chain volatility
- AI readiness - only 20% of facilities are considered AI-ready today
Nuclear and community impact enter the site selection calculus
Marlow's DCD Studio session was tagged with topics including nuclear power and community impact alongside the standard power and site selection themes[1]. That pairing reflects a shift BCS has documented in its research: 70% of survey respondents expect geopolitical events to accelerate locally generated renewable energy, with sustainability priorities now incorporating resilience, energy security, and community impact into site selection decisions. France, whose nuclear-heavy grid remains relatively unconstrained compared with other FLAP-D markets, is one beneficiary. The Nordics - with hydro and wind capacity and electricity costs averaging around 60% below other European markets - are another.
Spain has moved to a competitive grid access framework using capacity auctions across constrained power nodes in locations including Madrid, Aragón, and Andalusia, a model BCS has highlighted as prioritising operational readiness and accelerated delivery times.
The practical question for developers is whether the power infrastructure work - grid strategy, substation delivery, microgrid design - is being started early enough to avoid becoming the critical path. BCS's restructuring suggests many projects are still learning that lesson the hard way.
The images and texts on this page were created with the help of AI.
Related
 Markets & Policy
Beacon of Hope food pantry in Marshall, NC switches on first microgrid in state's $5 million Helene resilience program
Beacon of Hope Food Pantry in Marshall, NC has energised the first of 26 planned microgrids in a $5 million state program - but domestic-content rules are narrowing which sites can follow.
13 Oct 2026 Markets & Policy
Bannock County, Idaho set to vote this fall on reversing its 2024 utility-scale renewables ban
Bannock County commissioners will vote this fall on a new ordinance that would lift a March 2024 ban on utility-scale solar and wind - and add nuclear - after Hecate Energy pulled out entirely.
13 Oct 2026 Markets & Policy
First U.S. study of real commercial kitchens finds gas and propane appliances push NO₂ above EPA limits in 70% of sites
A peer-reviewed study published 6 October 2026 in Environmental Research Letters finds gas and propane commercial kitchens routinely exceed EPA nitrogen dioxide limits, while all-electric kitchens do not.
13 Oct 2026